

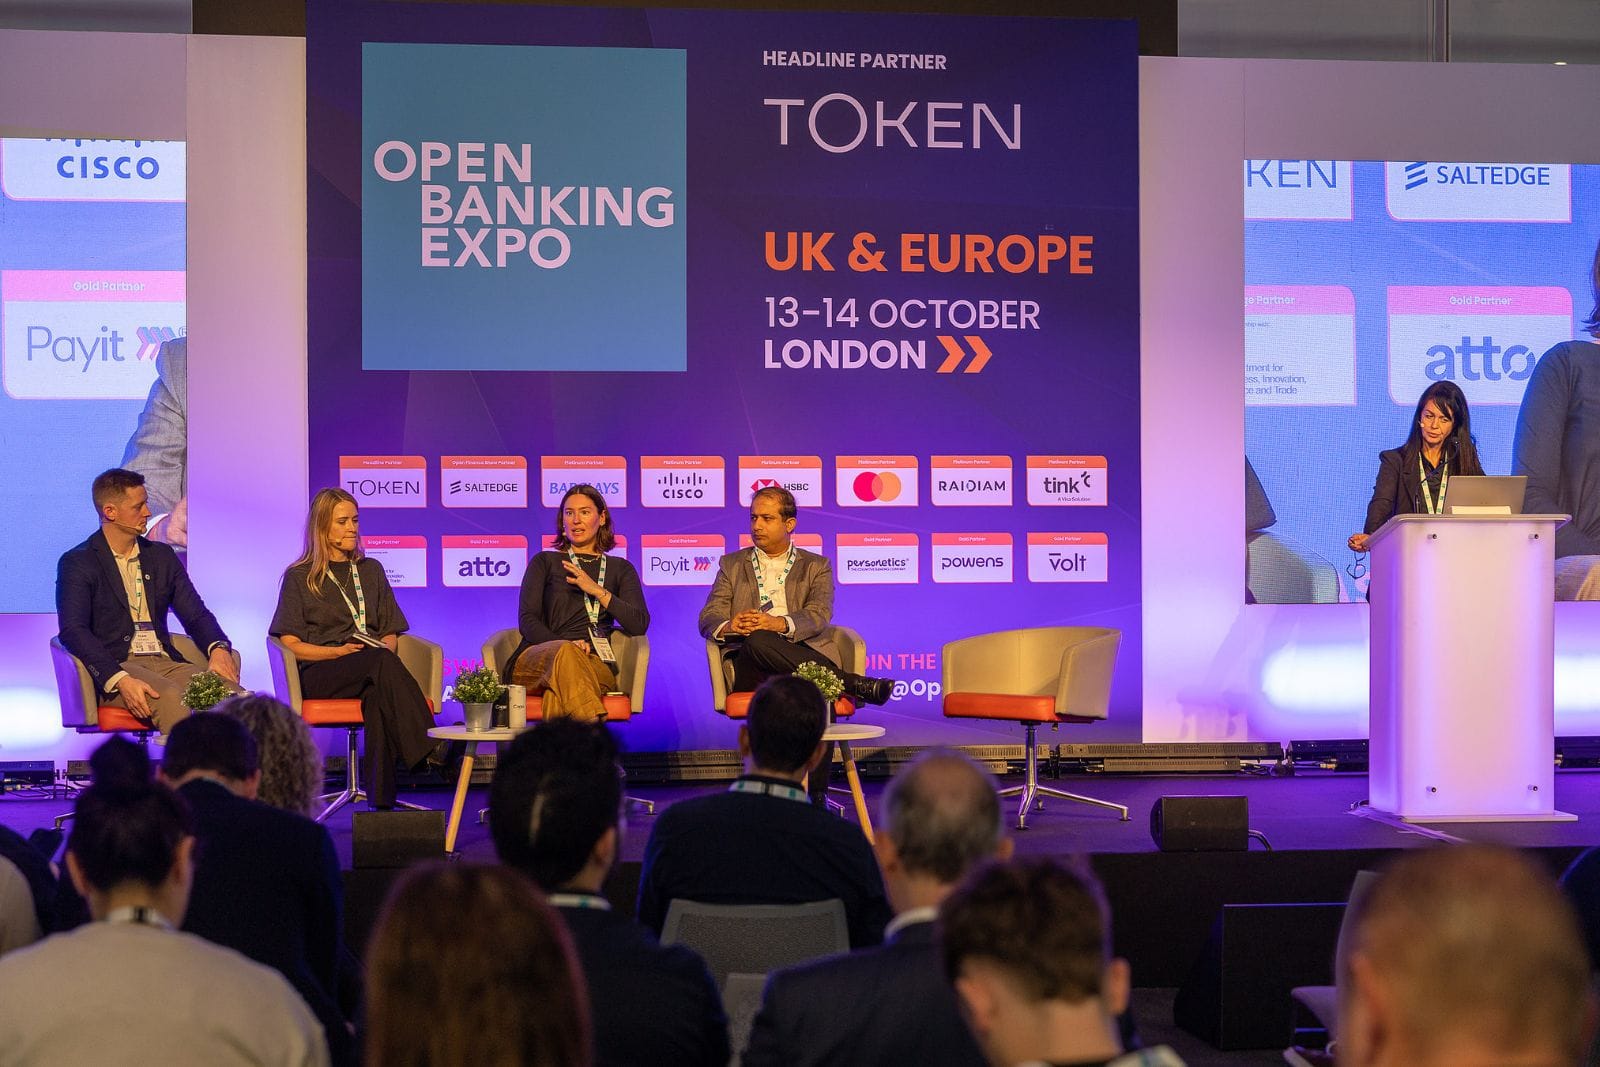
Open Banking payments must address gaps in reliability, consistency and transaction data if they are to become a mainstream alternative to cards, according to senior representatives from Plaid, Barclays, HSBC and Open Banking Limited.
Amanda Harrison, senior advisor at fscom
Speaking at Open Banking Expo UK & Europe 2026, industry leaders discussed how the UK’s National Payments Vision and unified payments framework could help modernise the country’s payment infrastructure while supporting innovation, competition and resilience.
During a Main Stage debate moderated by Amanda Harrison, senior advisor at fscom, argued that greater consistency across banks and payment systems is essential if businesses are to adopt Pay by Bank at scale.
He pointed to differences in payment limits, standards and reliability as barriers to widespread adoption.
“There are very few people, for example, that just offer pay by bank and no other methods. And until you can do that, I think you’ve got a gap,” he said.
Corbett contrasted this with the widespread acceptance of cards, arguing that businesses need confidence that alternative payment methods will work consistently across different use cases.
He also stressed that reliability must be treated as a fundamental requirement rather than a competitive differentiator.
Chris Corbett, head of product, UK and Europe at Plaid
Barclays calls for richer payment data
Michelle Stanley, director, digital banking at Barclays, said modernisation should focus on what businesses can achieve through payments rather than simply making transactions faster.
“I think success should mean that we stop actually talking about the payment,” she told delegates.
For corporate customers, she argued, the real opportunity lies in combining payment certainty with richer transaction data to enable automated reconciliation, real-time treasury management and more efficient business processes.
Stanley suggested that account-to-account payments still lag behind cards in the amount of information available to businesses.
“We need to see payments as a data product,” she said.
More detailed payment information could help businesses improve fraud detection, automate workflows and gain better insight into transactions, potentially making account-to-account payments more attractive.
Michelle Stanley, director, digital banking at Barclays
Stanley also called for greater international interoperability, arguing that cross-border payments should ultimately become as straightforward as domestic transactions.
Variable recurring payments seen as a key test
The panel identified commercial variable recurring payments (VRPs) as an important measure of progress under the National Payments Vision.
Corbett suggested that the UK Payments Initiative’s emerging commercial VRP scheme could provide an early indication of whether the industry can successfully establish new payment models.
“I think a good measure of success is can we make that successful?” he said.
His ambition was for recurring payments to become the largest form of Pay by Bank in the near term, demonstrating that the necessary commercial and technical foundations were in place.
Emily Rayment, head of public policy at Open Banking Limited, said common standards had already demonstrated their value in enabling innovation, but stressed that they must remain flexible enough to accommodate emerging technologies and payment use cases.
Emily Rayment, head of public policy at Open Banking Limited
She also highlighted the potential for Open Banking payments to become available through digital wallets, offering consumers an experience comparable to established payment methods.
“That could be transformative,” she said.
AI creates new opportunities and challenges
The discussion also explored the growing intersection between Open Banking and artificial intelligence.
Corbett said research conducted by Plaid indicated that half of UK consumers were already using AI to support financial decision-making, creating opportunities to combine financial data with AI-powered services.
Rayment acknowledged the potential of agentic payments but said questions around consent and liability would need to be addressed.
Meanwhile, Sovon Chatterjee, director, payment products at HSBC, emphasised that modernisation must be carefully coordinated to protect the resilience of existing payment systems.
Sovon Chatterjee, director, payment products at HSBC
He called for clear implementation roadmaps, industry collaboration and sufficient time for businesses to adapt to new infrastructure.
Describing the National Payments Vision as a significant opportunity for the sector, Chatterjee said:
“National Payments’ Vision is once in a generation kind of opportunity. Let’s make the most of it.”
The panel agreed that the ultimate measure of success would not simply be the introduction of new infrastructure, but whether it delivers safer, more dependable and more efficient payments for consumers and businesses.