

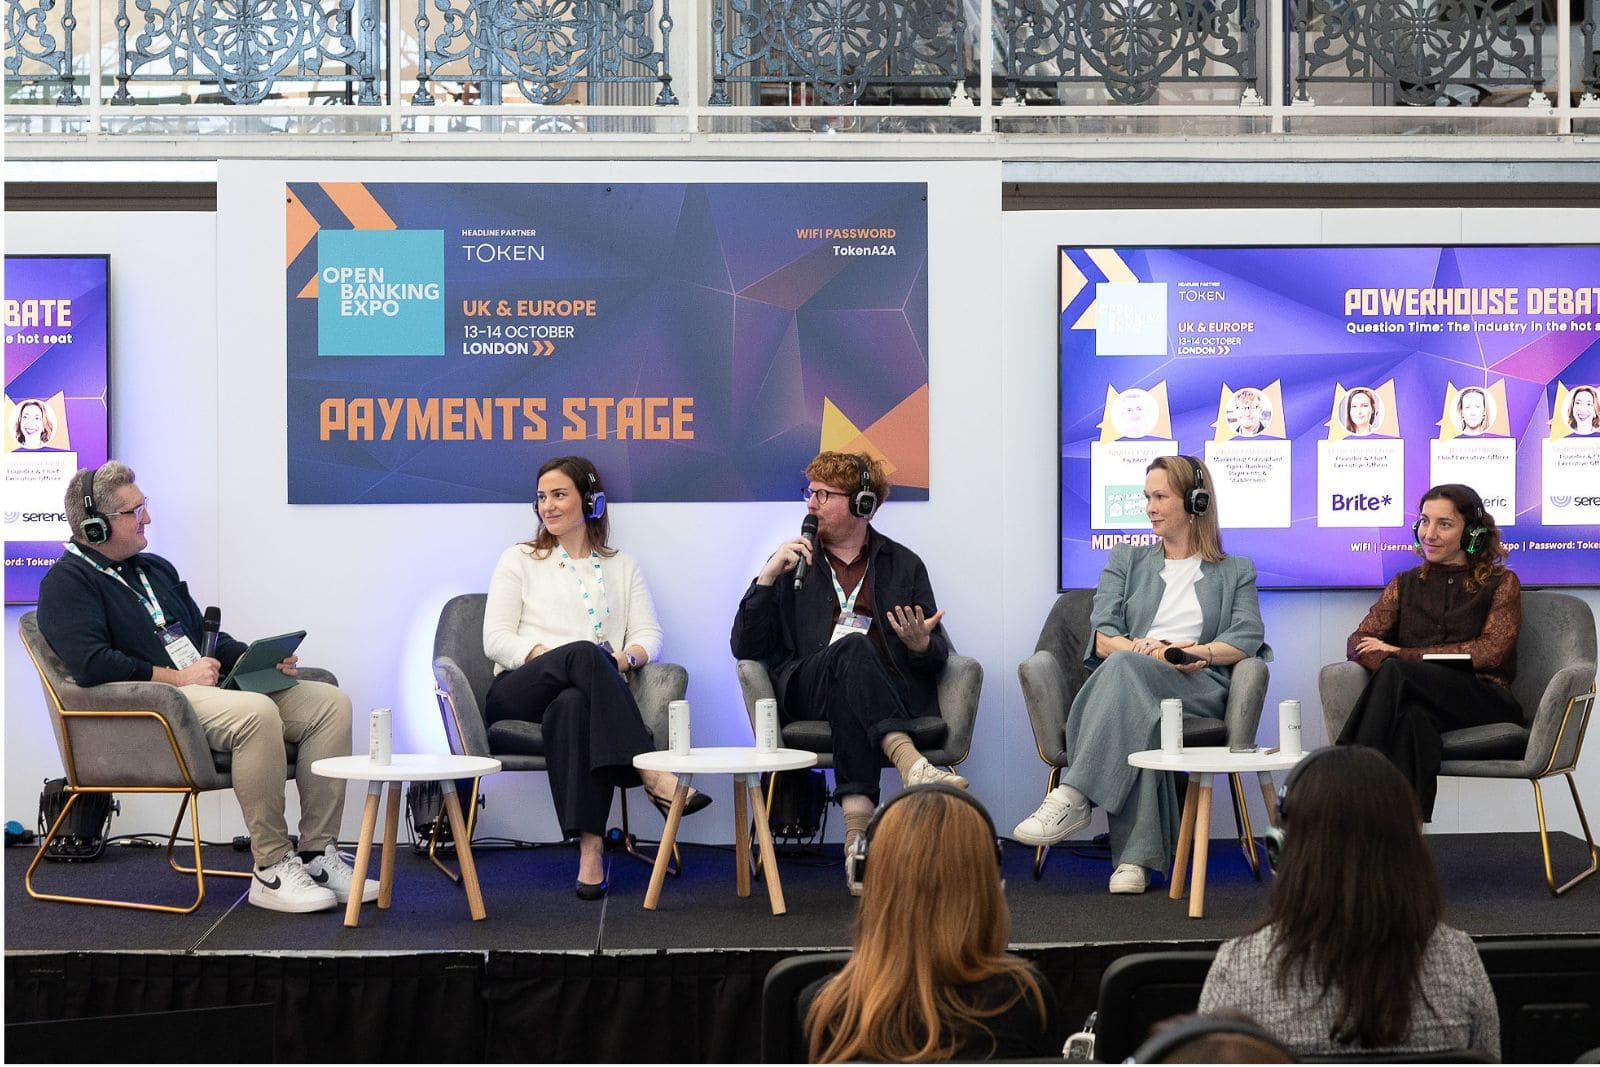
Commercial variable recurring payments (cVRP) are approaching a new phase of adoption, with industry leaders highlighting opportunities to give consumers greater control over recurring payments and help businesses deliver more flexible payment experiences.
Lena Hackelöer, founder & chief executive officer, Brite Payments
Speaking at Open Banking Expo UK & Europe 2026, payments specialists discussed how cVRP could expand beyond its initial use cases to support everyday transactions, including household bills and other recurring financial commitments.
During the interactive session Question Time: The industry in the hot seat, panellists explored what would be needed to achieve meaningful scale, alongside the role of consumer trust, commercial incentives and collaboration between financial institutions and fintechs.
Lena Hackelöer expressed confidence in the technology’s prospects, telling delegates: “We’re just on the brink of mass adoption.”
Greater flexibility for everyday payments
Adam Chapman highlighted the potential for cVRP to improve how consumers manage recurring household payments.
Using council tax as an example, he explained that direct debit arrangements can sometimes restrict customers to particular payment dates, making it difficult to adjust payments when their financial circumstances change.
Adam Chapman, marketing consultant – Open Banking, payments & stablecoins
He suggested that cVRP could provide a more flexible alternative, particularly for customers whose salary payment dates change.
“I think cVRP would solve for that too,” Chapman said.
Unlike traditional fixed recurring payment arrangements, commercial VRP enables customers to authorise future payments within agreed parameters, including limits on payment amounts and frequency.
The technology could therefore support more adaptable payment experiences while allowing customers to retain control over their permissions.
Instant payments deliver value beyond cost savings
The panel also explored where account-to-account payments are already creating tangible benefits for businesses and consumers.
Hackelöer identified financial services and digital goods as particularly promising areas, where immediate access to funds or services can make a meaningful difference.
She highlighted instant consumer loan disbursements as an example of how faster payments can improve the customer experience.
Savannah Price, founder & chief executive officer, Serene
Savannah Price similarly emphasised the importance of the time it takes for customers and businesses to receive money.
For consumers, faster refunds can provide earlier access to funds. For merchants, quicker settlement can support cash flow and help businesses meet financial commitments.
Price suggested that the benefits of instant payments become particularly compelling when speed creates a practical improvement in the customer’s financial position.
Consumer trust and incentives will support adoption
While the panel recognised the opportunities presented by account-to-account payments, speakers also discussed the importance of understanding existing consumer behaviour.
Chapman observed that consumers often remain loyal to familiar payment methods, even when alternative options are available.
He suggested that incentives, alongside trust and convenience, would play an important role in encouraging customers to try new payment experiences.
Price agreed that trust was central to adoption, particularly customers’ understanding of what happens if a transaction does not proceed as expected.
The discussion highlighted the importance of providing clear information and straightforward customer journeys as Open Banking payments become more widely available.
Fintech collaboration creates new opportunities
Beyond recurring payments, panellists discussed the increasingly collaborative relationship between established financial institutions and fintech providers.
Price described a shift towards broader ecosystem partnerships, with organisations combining specialist capabilities to improve different parts of the customer journey.
Chapman also pointed to the growing importance of fintech innovation within established financial services businesses.
Rather than viewing banks and fintechs solely as competitors, the panel highlighted the opportunities created when organisations work together to develop and distribute new payment solutions.
Building towards the next phase
The discussion reflected growing optimism about the role of commercial VRP in the evolution of Open Banking payments.
As more use cases emerge, the combination of flexible customer permissions, faster settlement and stronger industry collaboration could help recurring account-to-account payments become a more familiar option for consumers and businesses.
For the industry, the opportunity lies in demonstrating how the technology can improve everyday financial experiences, from managing household bills to accessing funds more quickly.