

As Open Banking and Smart Data continue to evolve, the financial services industry faces an increasingly important question: how can access to customer data translate into simpler decisions, better experiences and measurable outcomes?
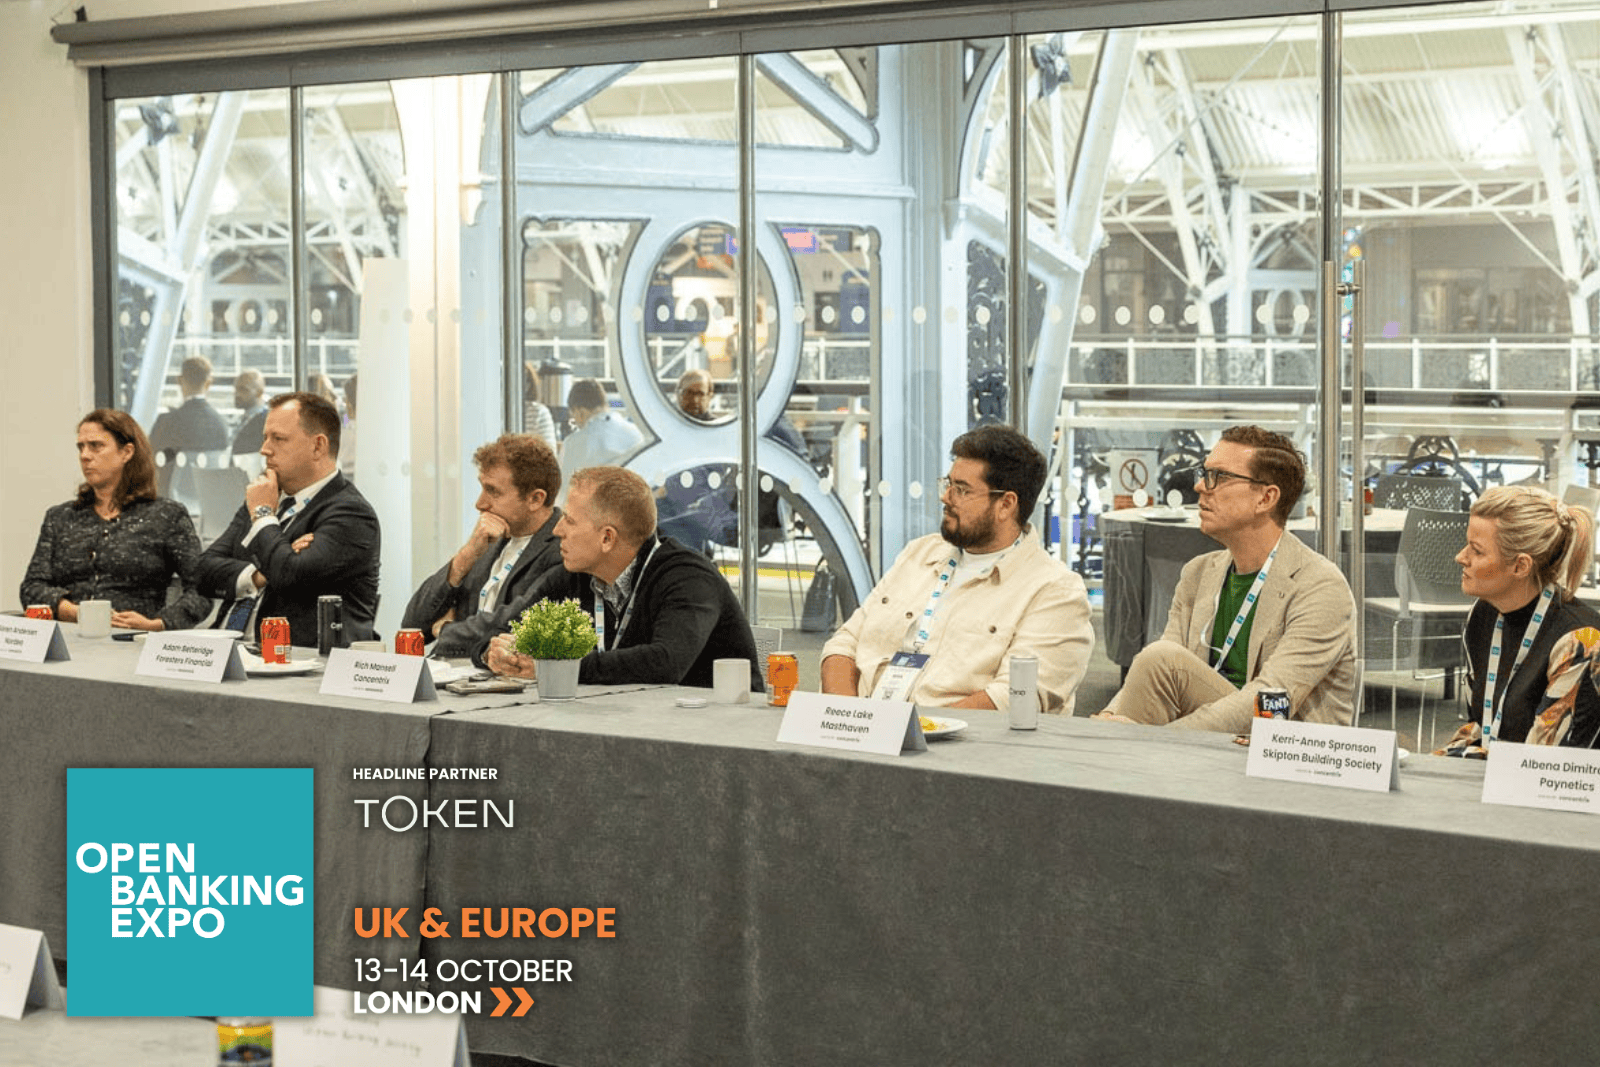
This question formed the basis of an exclusive, closed-door roundtable hosted by Concentrix at Open Banking Expo UK & Europe 2026.
Held under Chatham House Rule, the discussion brought together senior leaders from across the financial services ecosystem, including banks, building societies, specialist lenders, consumer finance providers, payments businesses and technology firms.
With expertise spanning operations, digital transformation, payments, customer propositions and data intelligence, the roundtable provided a forum to explore one of the industry’s most pressing challenges: how to move beyond the promise of Open Banking and Smart Data to deliver tangible, measurable value.
The conversation was framed around the journey from proof of concept to proof of value, examining the practical barriers to scaling data-driven propositions, the growing role of artificial intelligence (AI), and how financial institutions can translate increasingly sophisticated data capabilities into simpler, more effective customer experiences.
While Open Banking has made significant progress in enabling secure access to financial data, the industry’s next challenge is arguably more complex: turning that access into something customers genuinely value.
Moving beyond data access
For much of its development, Open Banking has focused on establishing the infrastructure, standards and permissions required to enable the secure sharing of financial information.
However, access to data is only the starting point.
The greater opportunity lies in how financial institutions interpret that information, apply intelligence and translate insights into meaningful actions.
Whether helping customers manage their finances, supporting more informed lending decisions or identifying opportunities for more personalised financial services, the value of Open Banking ultimately depends on what happens after the data has been accessed.
This raises an important question for the industry: are organisations designing services around the data they can access, or around the problems their customers need solving?
As the industry moves towards broader Smart Data initiatives, the distinction becomes increasingly significant.
Closing the gap between insight and action
A central theme of the roundtable was the potential disconnect between accessing financial data and translating it into practical customer or operational outcomes.
Financial institutions may have access to increasingly sophisticated datasets and analytical capabilities, but turning those insights into timely, relevant action remains a challenge.
The process requires more than technology alone.
Data must be connected across systems, interpreted within the appropriate context and integrated into customer journeys and operational workflows.
For example, identifying that a customer may be experiencing financial difficulty is only valuable if that insight enables a suitable response, whether through earlier engagement, more relevant support or an improved decision-making process.
Similarly, richer financial information can support lending assessments, but the benefit must ultimately be reflected in the speed, fairness or suitability of the decision.
The challenge is to ensure that the complexity of data integration and analysis remains behind the scenes, rather than becoming another burden for customers to navigate.
From proof of concept to proof of value
Despite continued investment in Open Banking, Smart Data and AI, moving from experimentation to large-scale deployment remains a significant consideration for financial services organisations.
Proofs of concept can demonstrate technical feasibility, but they do not necessarily establish commercial sustainability or measurable customer benefit.
Scaling requires organisations to address operational integration, governance, regulatory requirements and the ability to demonstrate a return on investment.
It also requires a clearer definition of success.
Rather than focusing solely on the volume of data accessed, the number of connections established or the sophistication of an AI model, organisations need to consider whether their propositions are delivering meaningful improvements.
These might include reduced customer effort, faster resolution times, more appropriate financial products, improved operational efficiency or better support for vulnerable customers.
The shift from proof of concept to proof of value therefore represents more than a change in terminology. It requires financial institutions to place measurable outcomes at the centre of their innovation strategies.
Adam Cox, co-founder and managing director of Open Banking Expo
Adam Cox, co-founder and managing director of Open Banking Expo, said: “Open Banking has spent years proving what’s technically possible. The next challenge is demonstrating what that actually means for customers and businesses.
“What’s particularly encouraging is the breadth of the financial services industry now engaging in these conversations. We’re moving beyond discussions about access to data and towards how that data can improve decisions, simplify experiences and deliver genuine commercial value.
“That’s where the next phase of growth will come from, and why bringing different parts of the industry together to tackle these challenges is so important.”
Could delegated banking transform the customer experience?
Another area of focus was the emerging concept of delegated banking, in which permissioned customer data, intelligence and automation work together to simplify financial decisions and actions.
The principle is straightforward: rather than expecting customers to interpret complex financial information and navigate multiple processes independently, technology can help anticipate needs, explain available options and support the next appropriate action.
In practice, this could involve more personalised financial guidance, proactive customer support or the automation of routine administrative tasks.
However, greater automation also introduces important questions around trust, transparency and accountability.
Customers need to understand how decisions are made, what information is being used and the extent to which they retain control.
The role of human judgement also remains critical, particularly in situations involving financial vulnerability, complex decisions or circumstances requiring empathy and discretion.
The opportunity is therefore not simply to automate more interactions, but to establish an effective balance between technology and human expertise.
Building trust into intelligent financial services
As AI becomes increasingly embedded within financial services, the importance of governance and explainability is growing.
The ability to generate insights or automate decisions does not remove the need for accountability.
Financial institutions must be able to demonstrate that data is being used appropriately, that decisions can be explained and that suitable safeguards are in place.
This becomes particularly important as organisations move towards more proactive and potentially autonomous financial services.
Rich Mansell, senior director and sector lead banking and financial services at Concentrix
For Smart Data propositions to achieve widespread adoption, customers must have confidence not only in how their information is accessed, but also in how it influences the services and decisions that affect them.
Trust cannot be treated as a secondary consideration. It needs to be embedded throughout the customer journey, from consent and data access through to decision-making and action.
Rich Mansell, senior director and sector lead banking and financial services at Concentrix, said: “The real opportunity in Open Banking is not just access to data, but turning that data into action that improves customer outcomes.
Organisations succeeding at scale are combining data, AI and operational expertise to simplify journeys, reduce friction and deliver measurable value.
As AI-driven services grow, strong governance, explainability and human oversight remain essential to building trust and accountability.”
The next phase of Open Banking
As Open Banking continues to mature and the possibilities of Smart Data expand, the industry’s focus is increasingly shifting towards practical application.
The infrastructure enabling secure data sharing remains essential, but it is no longer sufficient on its own to demonstrate success.
The next phase will require financial institutions, technology providers and industry stakeholders to connect data access with intelligence, operational execution and measurable customer outcomes.
For organisations looking to scale, the challenge is to move beyond demonstrating what technology can do and establish the value it creates.
Will Thompson, consulting director at Concentrix
Ultimately, the success of Open Banking and Smart Data may be measured less by the amount of information made available and more by whether that information helps customers make better decisions, access more appropriate services and navigate their financial lives with greater confidence.
Will Thompson, consulting director at Concentrix, said: “Open Banking has reached a point where success depends less on access alone and more on the ability to turn capability into commercially viable services.
The organisations that lead will be those that connect innovation with clear customer needs and scalable execution.”
The roundtable, “Harnessing Smart Data – Open Banking’s path to customer-centric value, from proof of concept to proof of value. Who’s actually scaling?”, was hosted by Concentrix at Open Banking Expo UK & Europe 2026. The discussion was held under Chatham House Rule.