

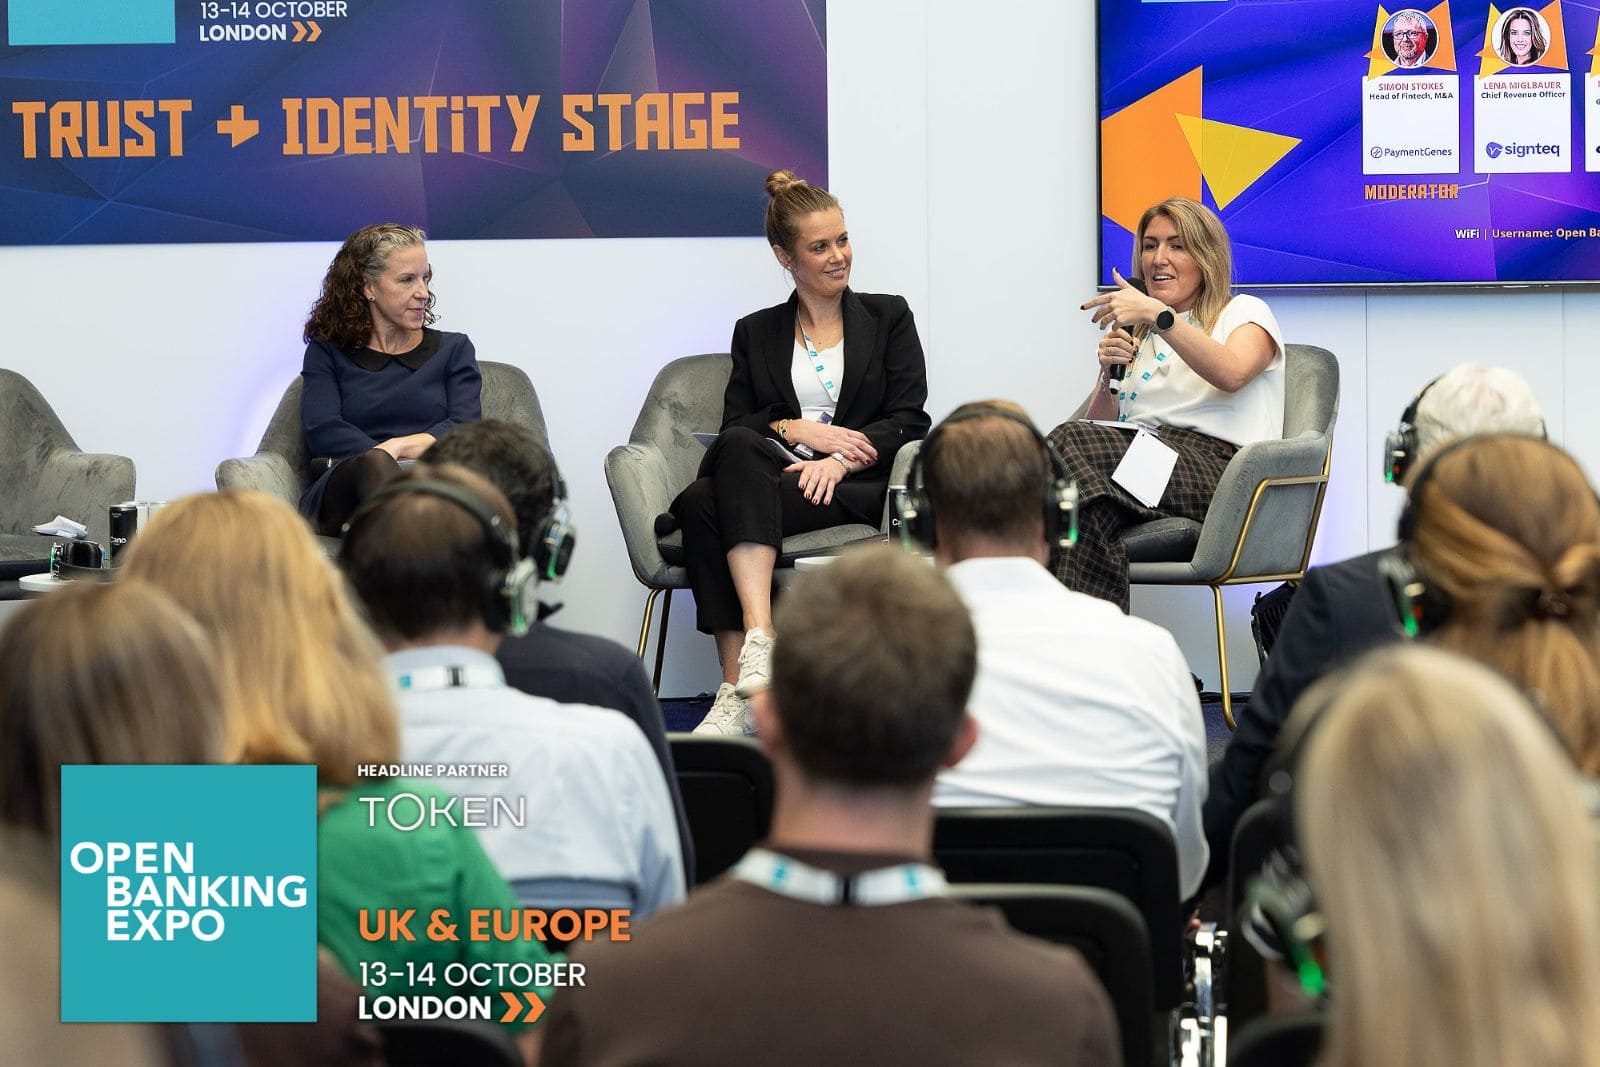
Financial services firms are increasingly being left to bear the cost of fraud originating on social media, online marketplaces and telecommunications networks, according to Capital One, amid calls for greater accountability across the wider digital ecosystem.
Speaking at Open Banking Expo UK & Europe 2026, Hannah Regan, who leads policy, government affairs and community at Capital One, warned that reimbursing fraud victims was not enough to tackle the underlying problem.
Hannah Regan, head of policy, government affairs & community, Capital One
During a panel discussion titled Fraud is winning. So what needs to change?, Regan argued that the current approach risks concentrating financial responsibility on banks while providing insufficient incentives for other industries to prevent scams.
“Reimbursement is not prevention, and I think the financial services sector is becoming like the default shock absorber for fraud that often originates outside of the financial services sector,” she said.
Fraud begins long before the payment
Regan cited UK Finance’s Annual Fraud Report 2026, which found that 66% of authorised push payment (APP) fraud cases originated online, while a further 17% began through telecommunications networks. Together, these channels accounted for 83% of reported APP fraud cases in 2025.
She argued that social media companies, search engines, online marketplaces and dating platforms all have a role to play in preventing fraudulent activity before victims are persuaded to transfer money.
The challenge, she suggested, is that these businesses do not necessarily face the same financial consequences as the institutions processing or reimbursing fraudulent payments.
“We need to make sure everyone has skin in the game,” Regan told delegates.
Her comments come as the payments industry continues to examine how liability and consumer protection should evolve alongside faster account-to-account payments and increasingly sophisticated fraud.
Police response must shift towards prevention
Helena Wood, who had been working with City of London Police on its fraud policing strategy, also called for a more preventative approach.
Wood said traditional policing methods, centred on arrests and prosecutions, could not adequately address the scale of fraud affecting UK consumers and businesses.
Helena Wood, head of economic crime strategy, City of London Police
Instead, she argued that law enforcement and industry needed to identify vulnerabilities earlier, share intelligence and disrupt fraudulent activity at scale.
Wood argued that policing needed to move away from a predominantly reactive approach, focused on arrests and prosecutions, towards preventing fraud at scale.
Wood highlighted the government’s online crime centre initiative as an example of efforts to bring policing and industry together to identify weaknesses in digital systems.
She said the initiative was at pilot stage and described better information sharing between law enforcement, financial services, telecommunications providers and online platforms as essential to its success.
Data sharing is critical
Wood pointed to Australia as an example of a market pursuing greater collaboration between banks, telecommunications providers and social media companies.
She argued that automated intelligence sharing and faster action against fraudulent content could help prevent scams before payments take place.
However, she acknowledged that meaningful progress would require changes to incentives and greater confidence among businesses about sharing fraud-related information.
The objective, she explained, should be to ensure that organisations can act on intelligence from other sectors rather than expecting consumers to identify every sophisticated scam themselves.
“We cannot rely on the consumer to be the first line of defence,” she said.
AI is making scams harder to identify
The panel also examined how artificial intelligence is increasing the sophistication of identity fraud, impersonation and social engineering.
Lena Miglbauer, chief revenue officer, Signteq
Lena Miglbauer, representing digital trust platform SignTeq, warned that checking individual identity documents or matching a face to an image was no longer sufficient.
Fraud prevention increasingly required organisations to examine signals across the entire customer journey, including devices, locations, telephone numbers and unusual activity.
Regan similarly highlighted the growing difficulty consumers face in identifying sophisticated impersonation attempts, including AI-generated communications.
She argued that businesses needed to develop more recognisable and trustworthy ways of communicating with customers while strengthening their ability to detect suspicious behaviour.
Shared responsibility, not reimbursement alone
While Regan supported protecting victims manipulated by sophisticated criminals, she questioned whether the current balance of responsibility created sufficient incentives to prevent fraud.
She argued that organisations involved throughout the journey, from the platform where a scam originates to the financial institution handling the payment, should take reasonable steps to prevent harm.
The discussion highlighted a wider challenge for Open Banking and the payments industry: faster and more convenient payment methods must be accompanied by fraud prevention measures that extend beyond the point of payment.
For Regan, the central issue is whether the organisations best placed to prevent fraud are also being given sufficient reason to act.