

Pay by Bank is changing the payments landscape forever. Pay by Bank recently reached a milestone, as the UK exceeded one billion cumulative transactions, with more than 15 million active users across the country. While in Europe, analysts predict three in four consumers in Europe will regularly use Pay by Bank by 2029.
What began as an alternative to cards is now a genuine disruptive force: real-time, secure, and seamless. Token.io’s annual industry survey recently found 93% of respondents reporting merchant demand, with 43% characterising this as high or very high. Open Banking Limited estimates a £4.4 billion market opportunity in the UK alone, while Juniper Research projects Open Banking payment transaction values will exceed $330 billion globally by 2027, with Europe accounting for the majority of that total.
Today’s most popular use cases — credit card repayments, account top-ups, savings funding — are expanding rapidly. The next wave of adoption will be driven by the introduction of Recurring Pay by Bank capabilities for automated e-money account top-ups, utility bill payments, pension contributions, charitable donations, and more.
Yet as Pay by Bank scales, a familiar pattern is emerging: fragmentation.
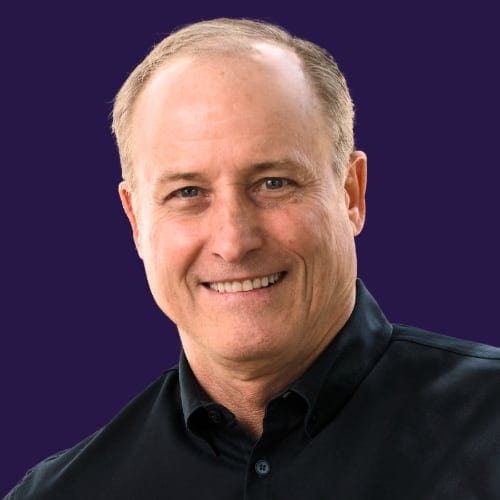
Todd Clyde, chief executive officer, Token.io
Across the UK and Europe, multiple Pay by Bank schemes have launched or are in development — UK Payments Initiative (live as of June 2026), giroAPI, SPAA, and S-Payments among them. Meanwhile, PSD3 and PSR1 near-final texts were published in April 2026, with formal adoption expected by late 2026, setting the regulatory stage for the next era of Pay by Bank across Europe.
Each Pay by Bank scheme brings its own functionality, geographic reach, dispute frameworks, and commercial models. This reflects a market responding to real demand: a scheme built for recurring payments in the UK solves different problems than one built for analogous functionality in Germany. Multiple providers investing and differentiating is what healthy competition looks like: evidence that the underlying opportunity is large enough to support it.
Open Banking regulation created a foundation. It did not create a finished product for every use case. Industry-led schemes emerged precisely because merchants, billers, and consumers needed more from Pay by Bank — recurring mandates, dispute resolution, and commercial frameworks that regulation alone could not deliver.
It is worth considering the alternative. Card payments achieved global scale by consolidating infrastructure into two dominant networks. That eliminated fragmentation — but also eliminated meaningful competition on pricing and innovation for decades. Merchants accepted the trade-off because no viable alternative existed.
Pay by Bank is taking the opposite path: multiple approaches, each optimised for different geographies, use cases, and commercial realities. More complex, but also how open markets drive better outcomes.
Fragmentation does and will create operational challenges. In the future, payment providers supporting Pay by Bank across the UK and Europe face integrating with multiple schemes, each with its own technical specifications and APIs. Managing that complexity directly impacts the ability to scale efficiently.
The key is not to resist fragmentation, but to abstract it. The organisations that succeed will be those that access multiple schemes through a unified infrastructure layer — benefiting from the reach and functionality of different networks without managing each one directly.
This requires an infrastructure partner that simplifies integration, harmonises rules, standardises payment flows where possible, and enables scalability across markets.
Pay by Bank is entering its next phase. Juniper Research projects global Open Banking API call volume will surpass 720 billion by 2029, and total Open Banking users globally will reach over 645 million — up from 183 million in 2025. Adoption is growing, scheme development is accelerating, and merchants and payment providers are looking beyond initial use cases toward performance, coverage, and functionality, like recurring and one-click Pay by Bank.
If managed effectively, this next phase has the potential to expand competition and deliver better outcomes for businesses and consumers. If not, fragmentation risks slowing one of the most significant structural shifts in modern payments.
Multiple schemes competing for the best outcome is a sign of a market maturing, not fracturing. What determines who wins next is not which scheme dominates — it is how seamlessly payment providers can plug into them all at once.
Todd Clyde is chief executive officer of Token.io
Token.io is Headline Partner of Open Banking Expo UK & Europe 2026 on 13-14 October at the Business Design Centre in London. Catch Todd Clyde’s Opening Keynote on the Main Stage on Day One of the Expo – view the agenda and find out more here. Speak to the Token.io team at Stand GR1 on the exhibition floor.